HI THERE I'm Yibei Hu
Data Scientist by training and a Problem solver by nature.

  • Georgia Tech | USC MS in Analytics | BSc in Business (Finance)
  • FRM Financial Risk Manager Level 2
  • 2 years Internship experience in sell side and audit/span>

About Me

I'm a graduate from the MS in Analytics program at Georgia Institute of Technology specializing in computational data science with a GPA of 3.91. I earned my Bachelor's degree from USC Marshall in May 2022 with honors and a GPA of 3.74. I standout with my knack for understanding the business landscape, allowing me to effectively contextualize and address various problems. This ability is further enriched by my expertise in SQL, Python, R, and Tableau, empowering me in data manipulation, visualization, and machine learning applications. I am actively pursuing exciting data scientist and data analytics opportunities starting 2024.
Programming Tools

  • Python
  • R
  • SQL
  • MongoDB
  • Tableau
  • PowerBI
  • Excel
  • MATLAB
  • Hive
  • PySpark
  • PyTorch
  • Tensorflow
  • Microsoft Azure

Modeling Skills

  • SVM
  • Time Series
  • A/B Testing
  • Random Forest/XGBoost
  • LLMs
  • CNN
  • Regression
  • Deep learning
  • HMM
  • Gaussian Process

Work Experience

May 2023 - Aug 2023

William Blair

Data Science Intern
  • Time-Series forecasting: Improved revenue forecast accuracy by 72% through the development of SARIMA and Gaussian Process Regression models. Facilitated downstream tasks such as real-time budget allocation.
  • Text Analytics: Leveraged PySpark to conduct text analyzing tasks such as FuzzyMatch on 0.8M unstructured text data regarding analyst-client interaction. Derived six features for rule-based analyst scoring.
  • Achieved a monthly reduction of 16 man-hours by automating the analyst review data pipeline on Azure Synapse. Created an interactive PowerBI dashboard for managerial data consumption.
Jun 2021 - Sep 2021

Industrial Securities Co., Ltd Inc

Quantitative Analytics Intern
  • Financial Bubble Detection Model: Successfully identified of 7 targeted bubbles within a 6-trading-day window by constructing a real-time bubble detection model utilizing the Generalized ADF test process.
  • Partnered with 2 researchers on 5+ financial reports on Alpha factor Stock Selection & ESG investment strategies. Completed tasks in data manipulation, time-series analysis, and feature engineering.
Jan 2021 - Apr 2021

Deloitte

Data Science Intern
  • Used SQL language to query and process clients’ key operation data. Complete data abnormality detection and authenticity evaluation.
  • Used Python to conduct data exploration. Conducted regression analysis on clients’ data, detected outliers and abnormalities and confirmed data authenticity.
  • Operated third-party data systems such as QuestMobile to conduct data assurance. Modified the draft report, and assisted in the final report writing.
Jun 2019 - Aug 2019

SAIC Mobility

Data Science Intern
  • Collaborated on the design of 4 campaigns, performed A/B tests to evaluate campaign performance, gained customer loyalty & increased active users by 23\%.
  • Tracked 20 App key performance indicators, including user growth, repurchase rate, and promotion effective rates using PowerBI dashboards, identified key consumer drivers and proposed 2 targeted marketing campaigns.

Latest works

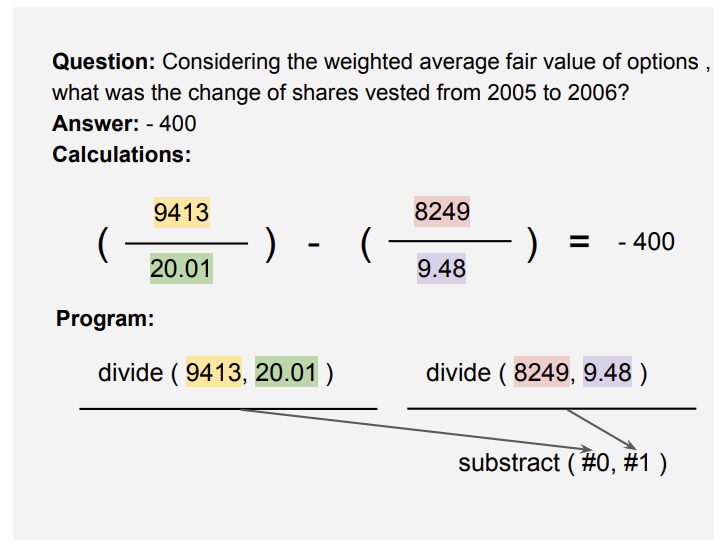
Numerical Reasoning on Financial Reports with LLM

Financial reports offer critical insights into a company's operations, but require costly manual review. To address this, we leveraged finetuned Large Language Models (LLMs) to distill key indicators and operational metrics from these reports basis questions from the user. We leverage the FinQA dataset to fine-tune both Llama-2 7B and T5 models for customized question answering. We achieved results comparable to baseline on the final numerical answer, a competitive accuracy in numerical reasoning and calculation.

Details GitHub

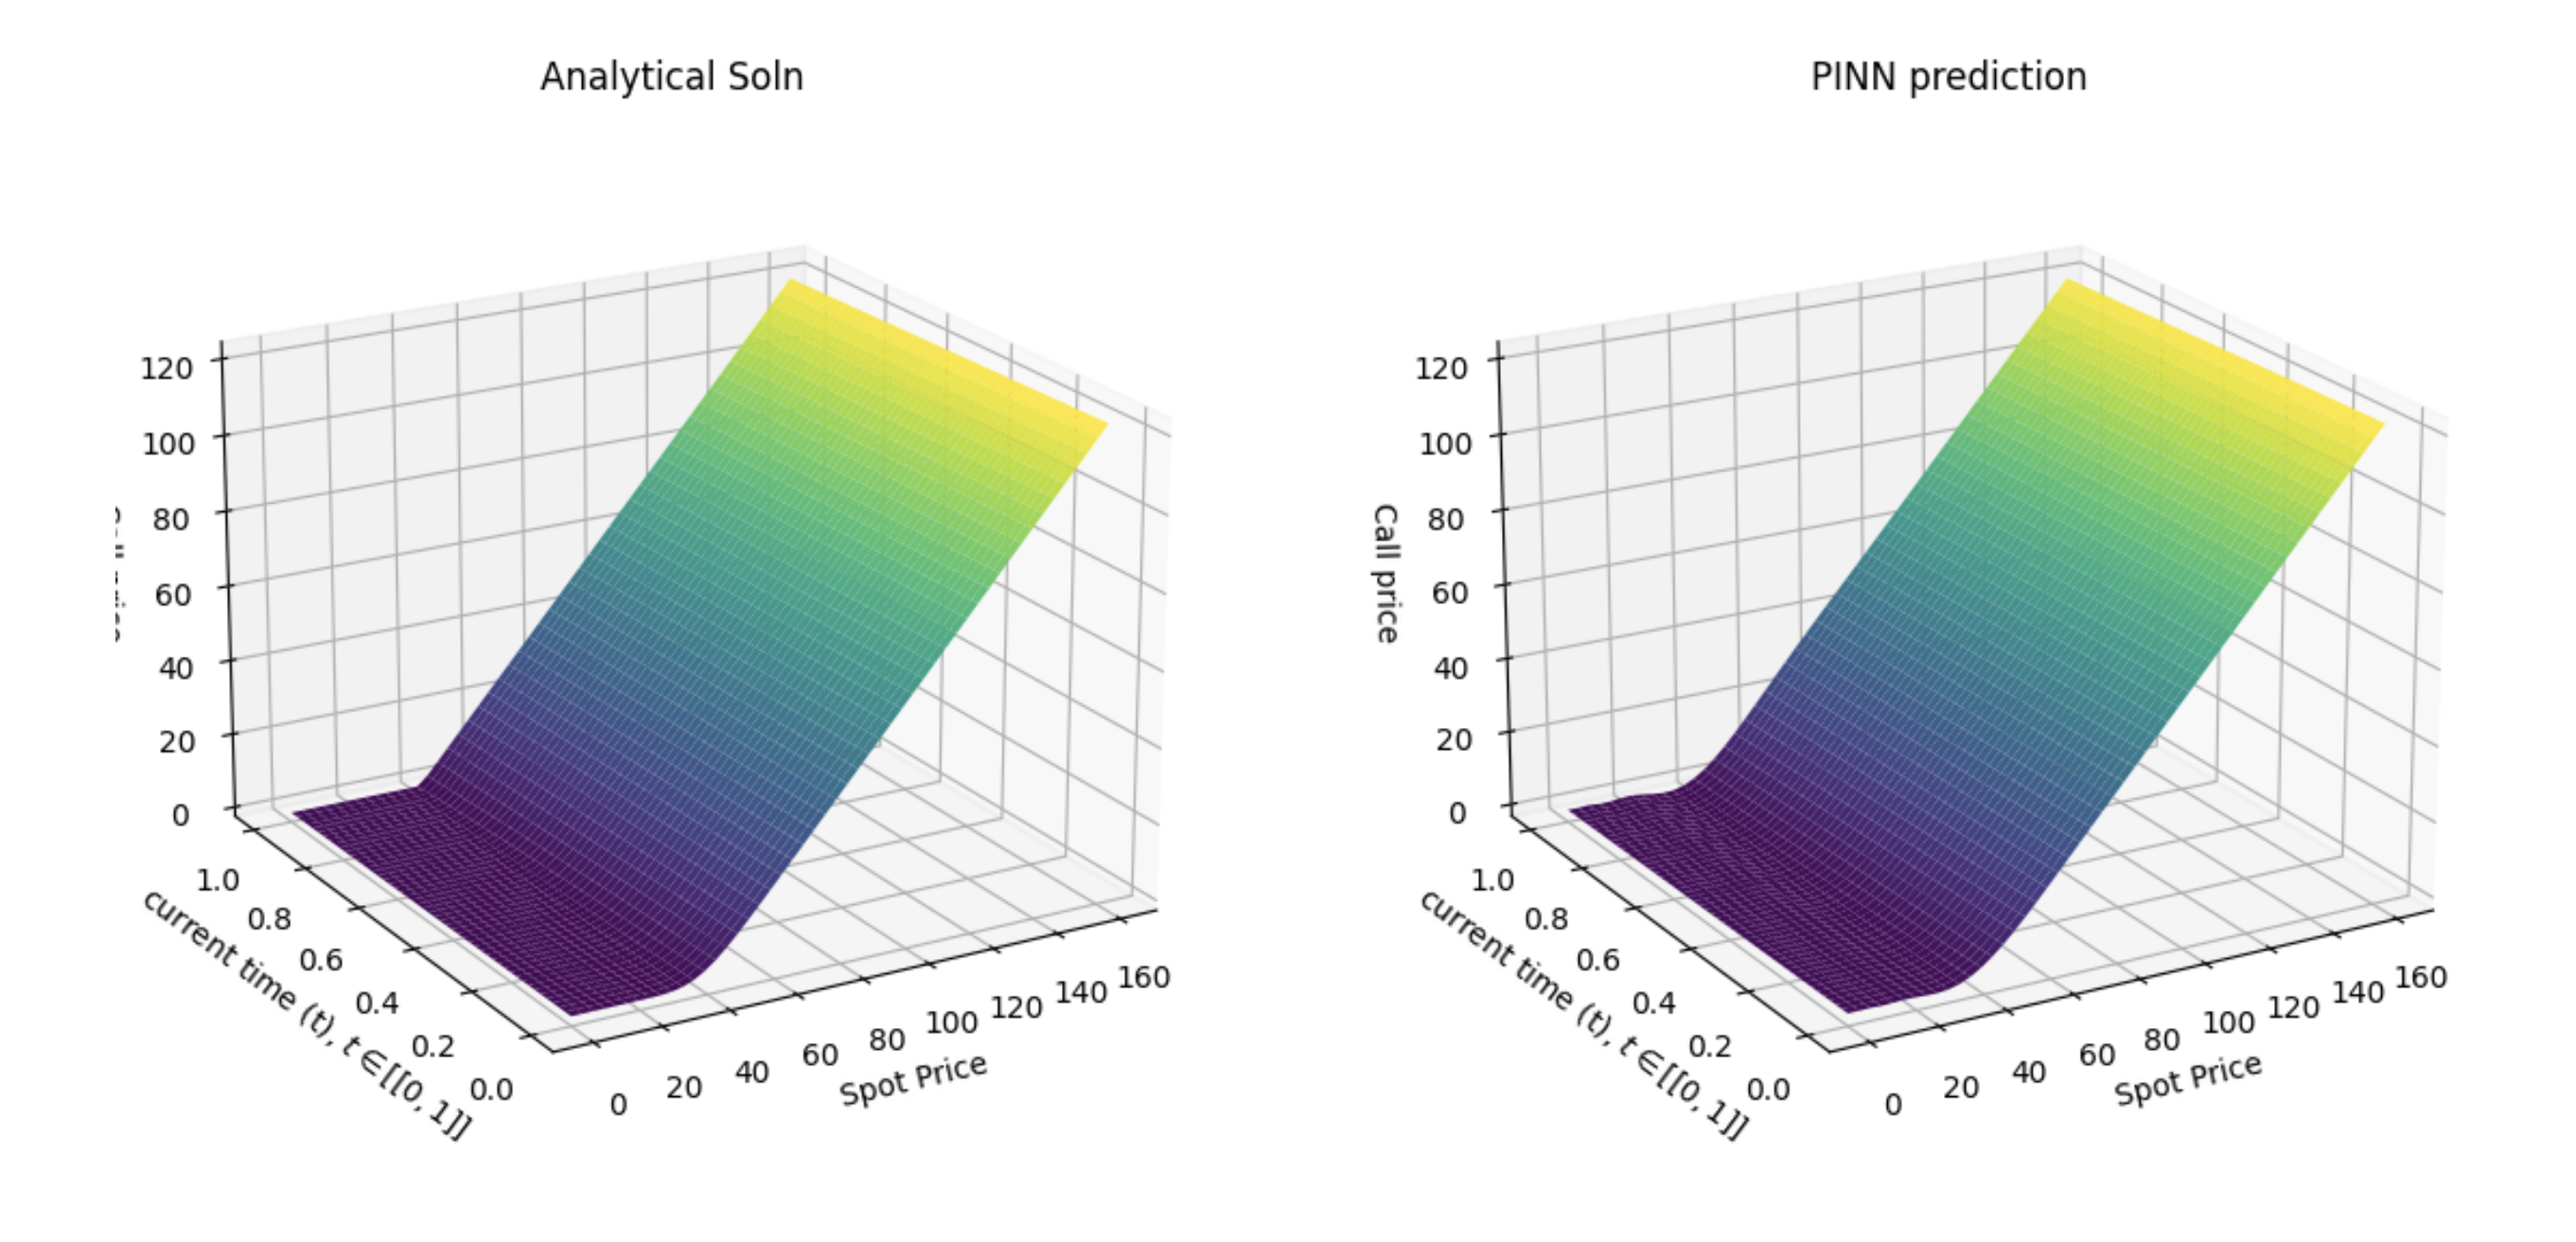
Scientific Machine Learning for Option Pricing

We apply a physics-informed deep-learning approach the PINN approach to the Black-Scholes equation for pricing American and European options. We test our approach on both simulated as well as real market data, compare it to analytical/numerical benchmarks. Our model is able to accurately capture the price behaviour on simulation data, while also exhibiting reasonable performance for market data. We also experiment with the architecture and learning process of our PINN model to provide more understanding of convergence and stability issues that impact performance.

Details GitHub

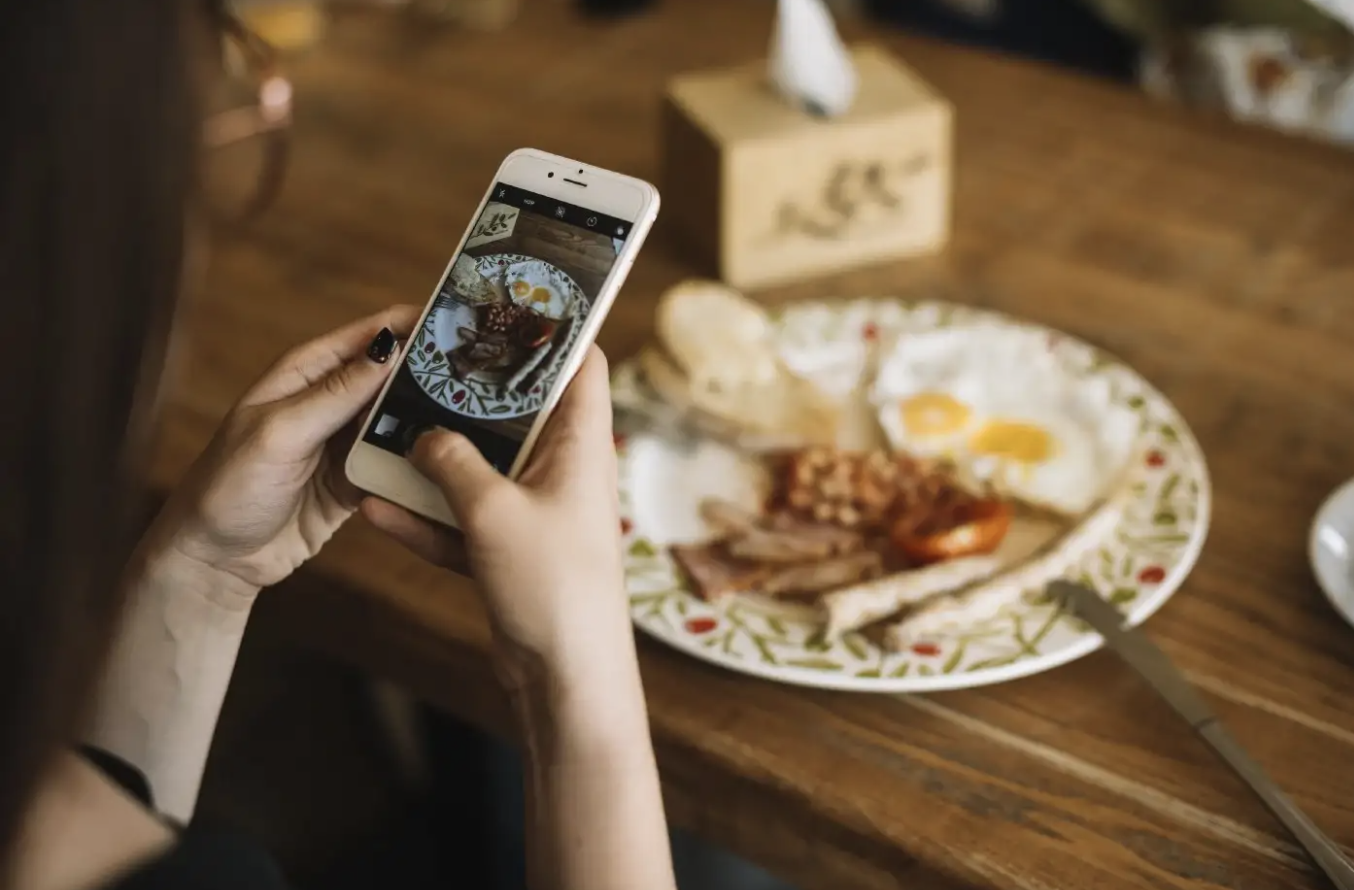
Robo Chef

Robo Chef is a program that takes a picture of food, recognizes its recipe, and gives recommendations based on the photo and previous user interactions. We first used a ResNet50 CNN architecture with transfer learning for image recognition. Then we built a food recommendation system based on SVD algorithm and NMF(non-negative matrix Factorization).

Details GitHub

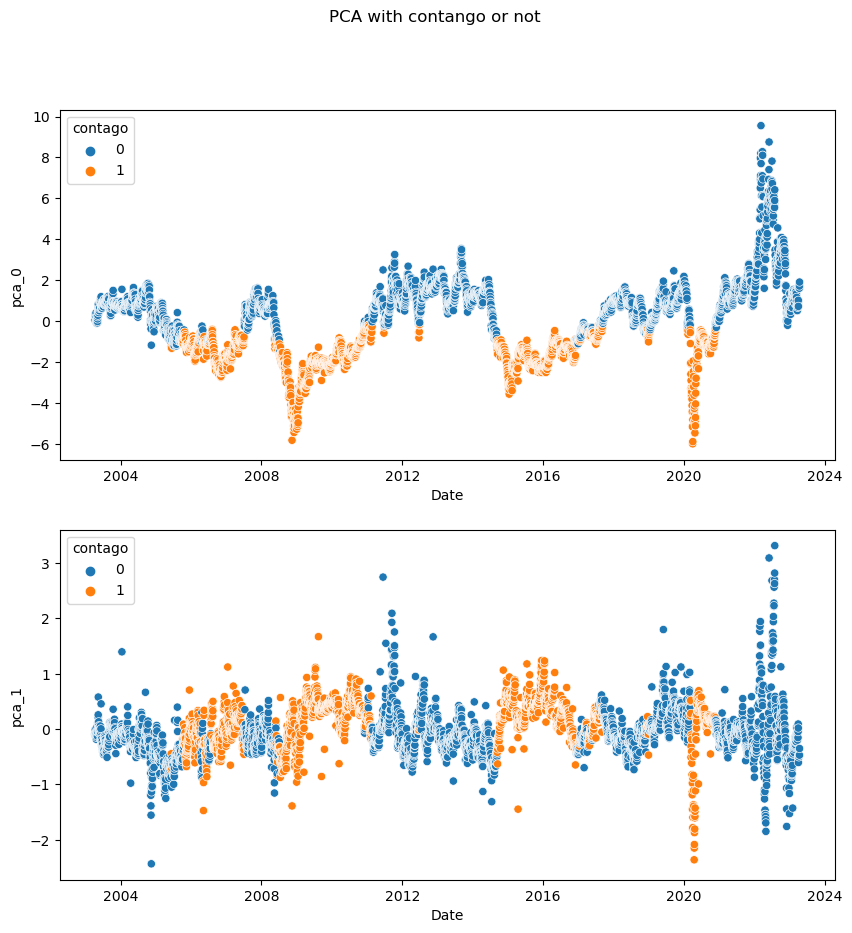
HMM-Based Forecasting of Brent Future Price Structure

The project involved the development of a predictive model for accurate detection of Brent futures price structures. This was achieved by utilizing Principal Component Analysis (PCA) and a Hidden Markov Gaussian Mixture model. The aim was to capture and analyze market behavior to make more informed trading decisions.

Details GitHub

Sales Forecasting for slow moving SKUs

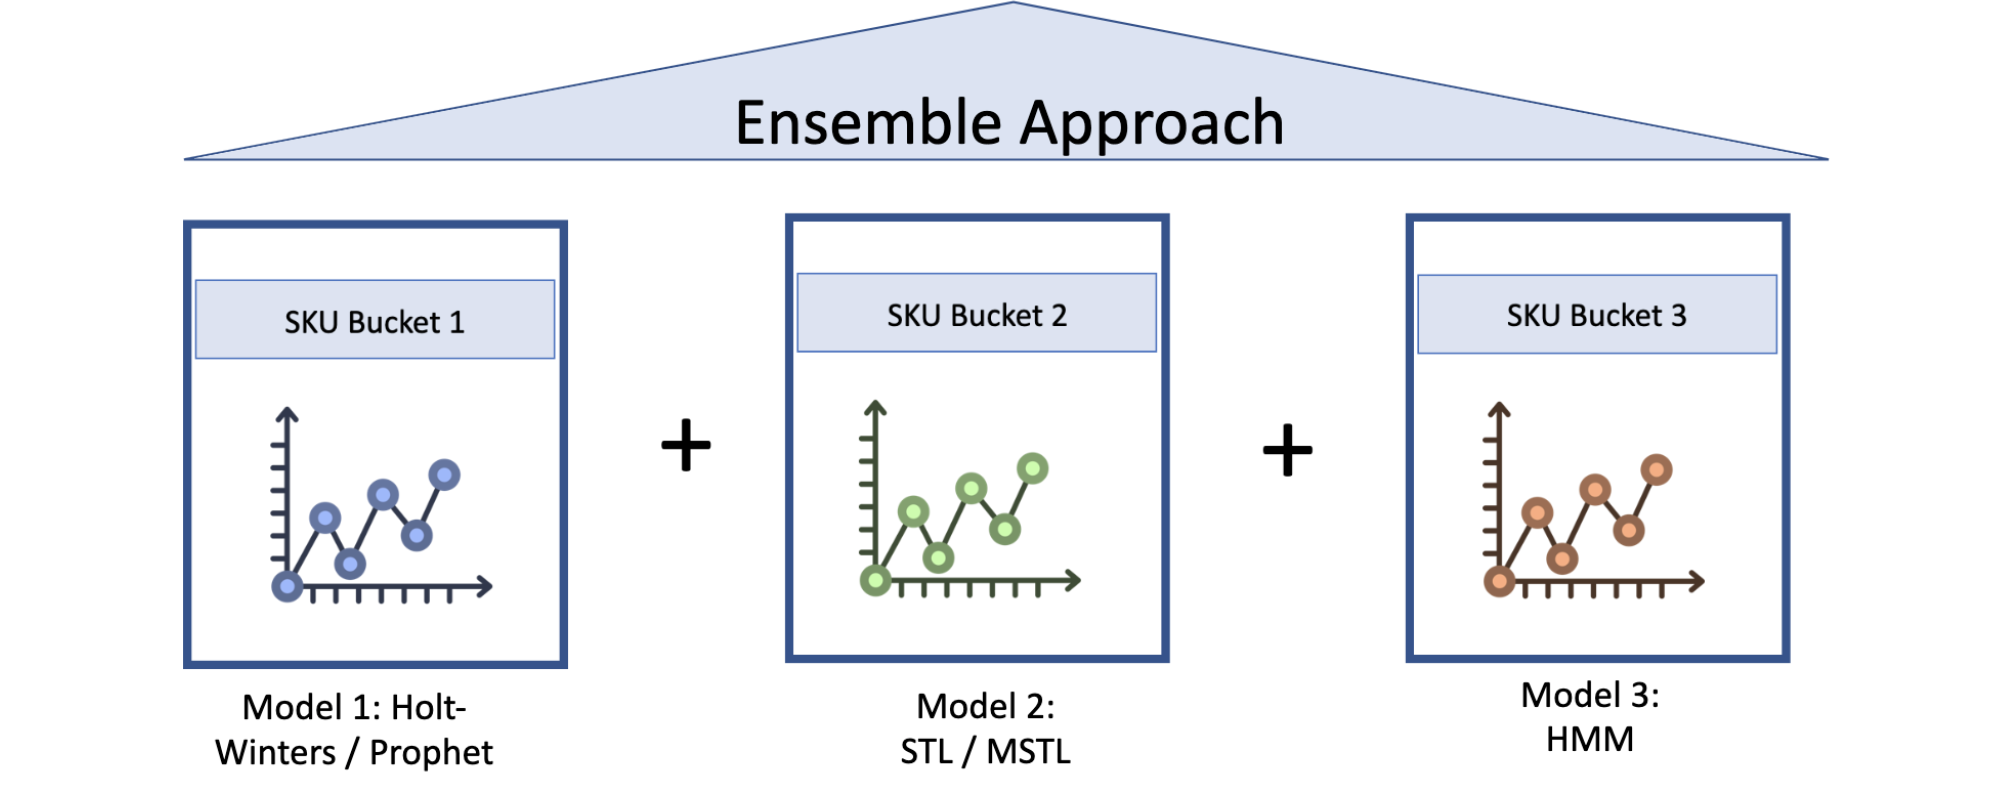
To predict the 7-day sales forecast for slow-moving items, an ensemble framework was constructed. This ensemble framework combined the power of three distinct models: Facebook Prophet, MSTL decomposition, and Hidden Markov models. The integration of these models led to the achievement of an impressively low Mean Squared Error (MSE) of 2.21. Importantly, this MSE was 58.23% better than that of the Null model, demonstrating the effectiveness of the ensemble approach in improving sales forecast accuracy and highlighting its potential for enhancing decision-making in inventory management and sales planning.

Details GitHub

Forecasting US Yield rates with Gaussian Process

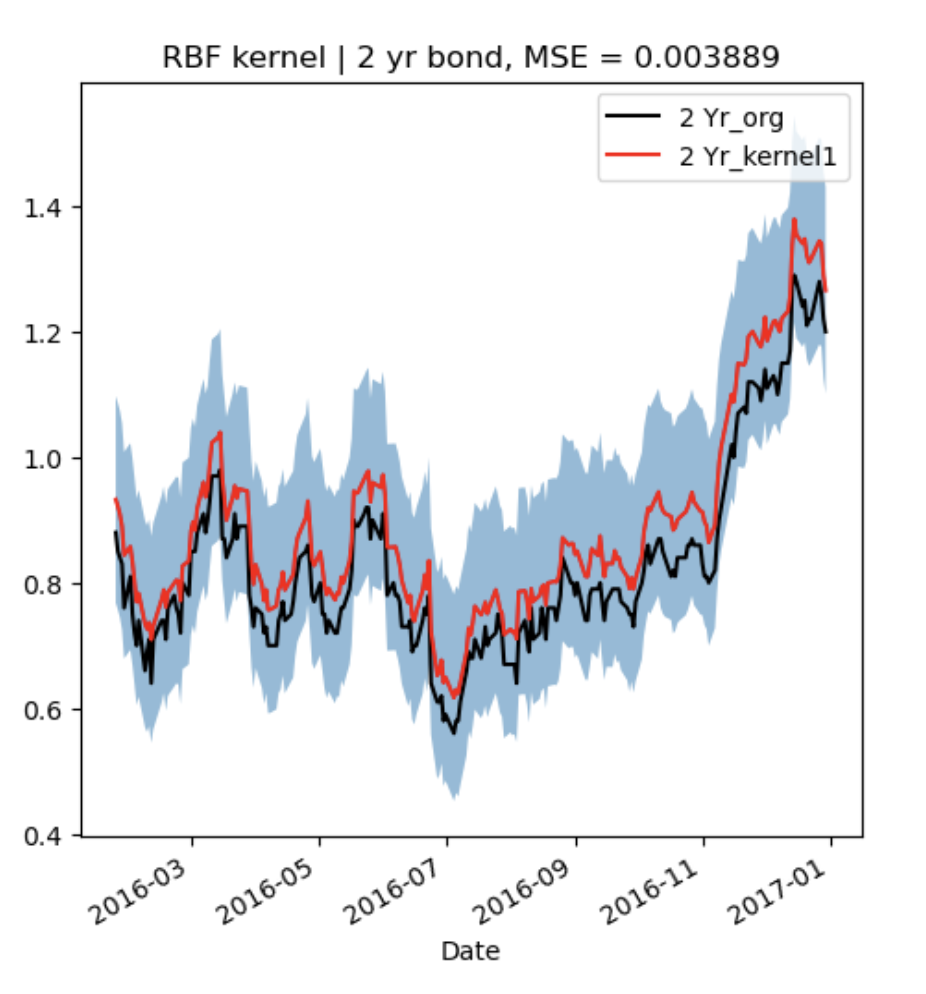
A robust forecasting model was developed in this project, utilizing Gaussian Process regression, a Bayesian machine learning framework, and fine-tuning the model using PyTorch. The model underwent experimentation with various kernels, including the RBFKernel, during training. This approach allowed for the creation of a highly adaptable and accurate forecasting tool capable of capturing intricate data patterns and relationships.

Details GitHub

World Happiness Rport

This data analytics and visualization project aims to determine the most critical contributors to a country's happiness score. Based on the world happiness report dataset from 2015 to 2022. I conducted regression analysis, feature engineering, and Tableau visualization to show my results.

Details GitHub